

Blog
15/09/2026
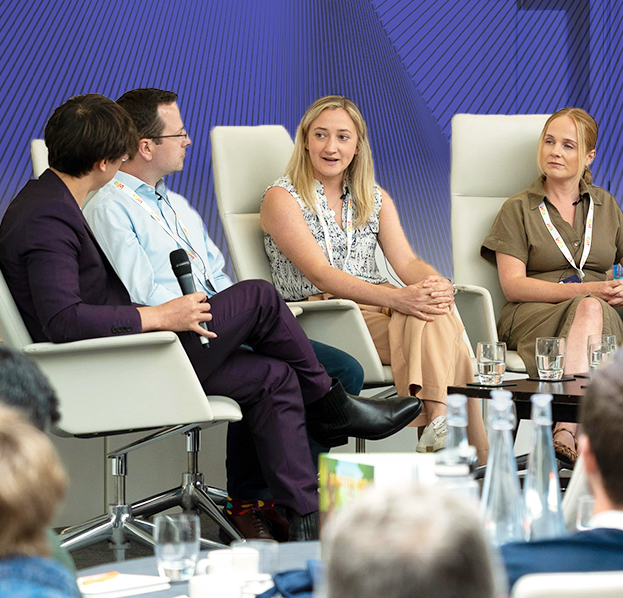
Emily Gillbanks wasn’t expecting to find a $54-billion expense buried in her client’s books.
But that’s what the Bennett Brooks and Company Technical Audit Director uncovered while reviewing the company’s administrative expenses in Inflo Explore.
“It became apparent straight away that something wasn’t quite right with the data,” Gillbanks described during a customer panel session at the recent Inflo Live UK 2026 conference. “Something needed to be investigated.”
The culprit turned out to be an erroneous staff expense posting that had been entered and reversed within the same month. In a traditional high-level analytical review, it may have remained hidden.
Instead, the anomaly surfaced immediately.
More important was what it revealed. Behind that spike sat process weaknesses, missing controls, and risks that deserved attention long before fieldwork reached its conclusion.
“This was instant, and we could see it straight away,” Gillbanks added.
The story reflected a common theme heard throughout the session: analytics isn’t about producing more data. It’s about helping auditors see what matters sooner, understand it more deeply, and make better decisions because of it. That’s the difference between having data and turning it into intelligence.
Gillbanks was joined on the panel by Lotte Williams, Head of Retail and eCommerce at HaysMac, and James Berridge, Director of Data Analytics at Saffery. Each shared how analytics is changing the way their firms engage clients, conduct the audit, and assess risk.
Remembering life before analytics
For all three panellists, the pre-analytics world looked remarkably similar:
For Gillbanks, much of the work felt like “sieving through invoices” while struggling to extract meaningful value. As sample sizes increased, journal testing became increasingly labour-intensive.
At HaysMac, Williams described how, as traditional sample caps disappeared, audit teams faced the prospect of testing hundreds of items instead of dozens. The question quickly became: how do you reduce effort without reducing quality? More importantly, how do you make the work more valuable?
For Berridge, inconsistency was one of the biggest issues at Saffery. Different teams assessed journal risks in different ways. Some performed sophisticated analysis in Excel. Others relied heavily on judgement and selected transactions that simply looked unusual. The result was significant variation across engagements.
None of the panellists described a quality problem.
They described a visibility problem.
Their teams had the expertise. What they didn’t always have was a fast way to see what mattered inside increasingly large datasets. Instead of spending time understanding risk, auditors were often spending their days hunting for it.
When analytics becomes part of the audit
Every firm represented on the panel took a slightly different route, but analytics now sits firmly within their audit processes.
At Saffery, analytics began with journal testing and continues to play a central role in helping teams assess risk consistently.
At HaysMac and Bennett Brooks, multiple analytics modules are now embedded into planning activities, helping teams identify patterns, challenge assumptions, and refine their approaches before they request large volumes of supporting documentation.
The result isn’t simply a more efficient version of the traditional audit. It’s a more intelligent audit built around data from the start.
The moments that changed minds
For Williams, the power of analytics emerged through gross margin analysis. Working primarily with retail clients, her team expected profitability trends to remain relatively consistent.
When one client’s year-end margin suddenly spiked, analytics quickly revealed the cause: deferred income postings had not yet been completed.
Rather than basing decisions on distorted data, the team was able to pause, discuss the issue with the client, and ensure testing was built on a more reliable foundation.
Berridge offered a different kind of success story. It wasn’t about finding an anomaly. It was about changing how auditors think.
Inspired by the visual power of Inflo Cascade – Revenue, one engagement team began exploring whether similar techniques could help them better understand a complex stock system. The tool ultimately sparked a broader conversation about what was possible and encouraged the team to experiment with new approaches.
That’s when analytics becomes more than a testing tool.
James’s story wasn’t about finding an exception. It was about curiosity. Suddenly the conversation wasn’t “what can we test?” but “what else can this data tell us?” That shift is fundamental to audit’s Intelligence Era: data becomes a source of better questions, not simply more evidence.
Better data, better conversations
Something interesting happens when clients can see the same patterns auditors see. The conversation changes. Instead of debating samples and spreadsheets, both sides are looking at the same story emerging from the data.
In the case of the expense anomaly identified by Gillbanks’s team at Bennett Brooks, the graphs became a shared point of discussion. Auditor and client explored the data together, adjusting views and examining patterns collaboratively.
The exercise gave management a new perspective on their own business, while helping the audit team understand underlying processes more deeply.
Then something unexpected happened.
The client didn’t file the analytics report away with the rest of the audit documentation. They circulated it internally and shared it with their parent company in the United States.
That’s not something you see every day for an audit output.
The report gave people inside the organization a clearer view of what was happening in the business.
It also strengthened trust.
When clients can see how conclusions are reached and watch risks emerge through the data itself, audit becomes more transparent, more collaborative, and ultimately more valuable. That value is where intelligence creates the conditions for growth: stronger relationships, greater differentiation, and an audit that clients don’t view as interchangeable.
Looking ahead
All panellists agreed they’re still in the early chapters of their analytics story. They discussed the potential for artificial intelligence to help auditors interpret data more effectively, provide guidance on what good analytical procedures look like, and increase confidence when determining appropriate levels of reliance.
But none of the panelists saw AI as a replacement for auditor judgement.
The opportunity was simpler than that:
Help auditors spot what matters sooner.
Help them ask better questions.
Help them spend less time searching through data and more time understanding what it’s saying. That’s what analytics makes possible.
AI will contribute to that, but it’s only one part of the story. Intelligence also comes from data, analytics, methodology, client context, and professional judgement working together.
See what your firm’s data has been trying to tell you with Inflo Audit Data Analytics.
Join firms worldwide in embracing the future of auditing with Inflo. Work smarter, deliver better audits, and exceed expectations.
Book a demoBook a demo today and discover how Inflo can transform your audit practice.